Preliminary reassessment proceedings generally require statutory remedies unless jurisdiction is wholly absent or mandatory conditions are patently br...
Agricultural land classification requires cumulative factual indicators, while industrial-purpose land and absent agricultural use defeat reinvestment...
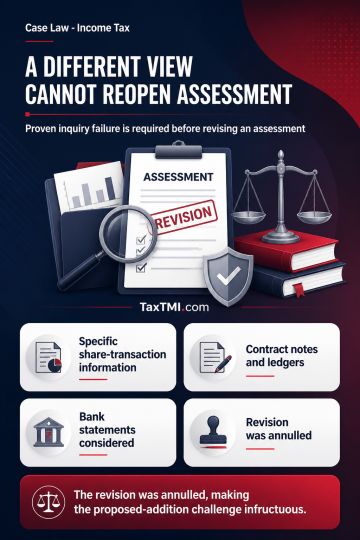
Revision for inadequate inquiry under section 263 requires a showing that the Assessing Officer's inquiry was inadequate; a different revisional view alone does not satisfy Explanation 2(a). Reassessment initiated on specific information about alleged penny-stock share transactions involved queries and consideration of contract notes, brokerage and ledger records, and bank statements. Acceptance of short-term capital gains as genuine was therefore a plausible view. The reassessment order was not erroneous or prejudicial to Revenue interests, the revision was annulled, and the proposed-addition challenge became infructuous.
Revision for inadequate inquiry under section 263 requires a showing that the Assessing Officer's inquiry was inadequate; a different revisional view alone does not satisfy Explanation 2(a). Reassessment initiated on specific information about alleged penny-stock share transactions involved queries and consideration of contract notes, brokerage and ledger records, and bank statements. Acceptance of short-term capital gains as genuine was therefore a plausible view. The reassessment order was not erroneous or prejudicial to Revenue interests, the revision was annulled, and the proposed-addition challenge became infructuous.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 1978