Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
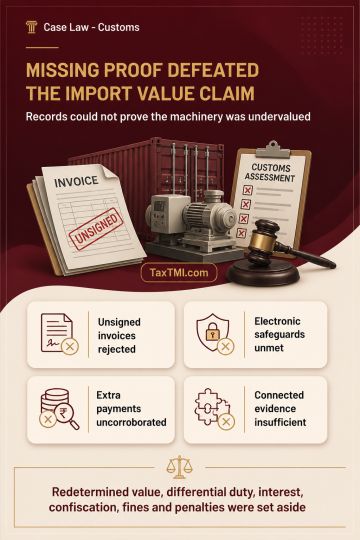
Unauthenticated electronic invoices and computer printouts could...
Electronic-record authentication requirements defeated the undervaluation claim, resulting in cancellation of reassessed value, duties, confiscation, fines and penalties.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Unauthenticated electronic invoices and computer printouts could not establish undervaluation of imported heavy earth-moving machinery. Unsigned invoices did not attract the statutory presumption under section 139, while computer-generated invoices were inadmissible because safeguards for electronic records under section 138C(2) were not met. Statements alleging extra remittances to the overseas supplier lacked independent corroboration and admissible supporting evidence. Substantially identical evidence from the same investigation had already been found insufficient in connected proceedings. The redetermined value, differential duty, interest, confiscation, redemption fine and penalties were set aside, with consequential relief.
Unauthenticated electronic invoices and computer printouts could not establish undervaluation of imported heavy earth-moving machinery. Unsigned invoices did not attract the statutory presumption under section 139, while computer-generated invoices were inadmissible because safeguards for electronic records under section 138C(2) were not met. Statements alleging extra remittances to the overseas supplier lacked independent corroboration and admissible supporting evidence. Substantially identical evidence from the same investigation had already been found insufficient in connected proceedings. The redetermined value, differential duty, interest, confiscation, redemption fine and penalties were set aside, with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932