Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
Unauthenticated electronic invoices and computer printouts could...
Electronic-record authentication requirements defeated the undervaluation claim, resulting in cancellation of reassessed value, duties, confiscation, fines and penalties.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
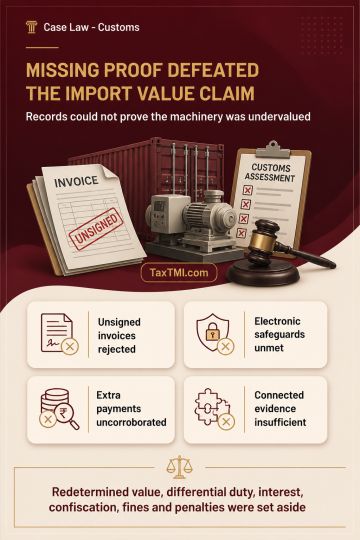
Unauthenticated electronic invoices and computer printouts could not establish undervaluation of imported heavy earth-moving machinery. Unsigned invoices did not attract the statutory presumption under section 139, while computer-generated invoices were inadmissible because safeguards for electronic records under section 138C(2) were not met. Statements alleging extra remittances to the overseas supplier lacked independent corroboration and admissible supporting evidence. Substantially identical evidence from the same investigation had already been found insufficient in connected proceedings. The redetermined value, differential duty, interest, confiscation, redemption fine and penalties were set aside, with consequential relief.
Unauthenticated electronic invoices and computer printouts could not establish undervaluation of imported heavy earth-moving machinery. Unsigned invoices did not attract the statutory presumption under section 139, while computer-generated invoices were inadmissible because safeguards for electronic records under section 138C(2) were not met. Statements alleging extra remittances to the overseas supplier lacked independent corroboration and admissible supporting evidence. Substantially identical evidence from the same investigation had already been found insufficient in connected proceedings. The redetermined value, differential duty, interest, confiscation, redemption fine and penalties were set aside, with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI