Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
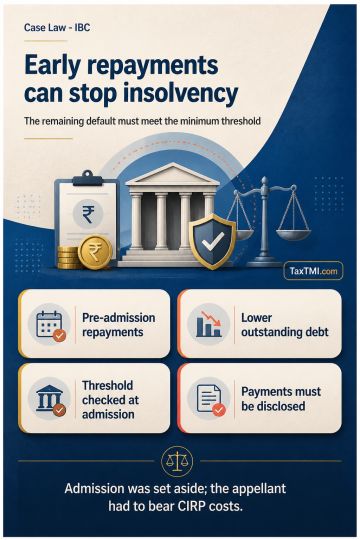
Corporate insolvency admission requires the outstanding default on the date of admission to meet the statutory minimum threshold. Part-payments made before admission reduce the debt in default for this purpose, and financial creditors must disclose those payments to the Adjudicating Authority. Where the remaining default falls below the threshold, admission of the insolvency application cannot be sustained. The admission was set aside because pre-admission repayments reduced the outstanding default below the applicable minimum, and CIRP costs were directed to be borne by the appellant.
Corporate insolvency admission requires the outstanding default on the date of admission to meet the statutory minimum threshold. Part-payments made before admission reduce the debt in default for this purpose, and financial creditors must disclose those payments to the Adjudicating Authority. Where the remaining default falls below the threshold, admission of the insolvency application cannot be sustained. The admission was set aside because pre-admission repayments reduced the outstanding default below the applicable minimum, and CIRP costs were directed to be borne by the appellant.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937