Concessional corporate tax option under section 115BAA survives procedural documentary lapses when statutory compliance and earlier exercise are estab...
Penny-stock additions require transaction-specific evidence; general investigation material alone cannot establish undisclosed income or accommodation...
Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
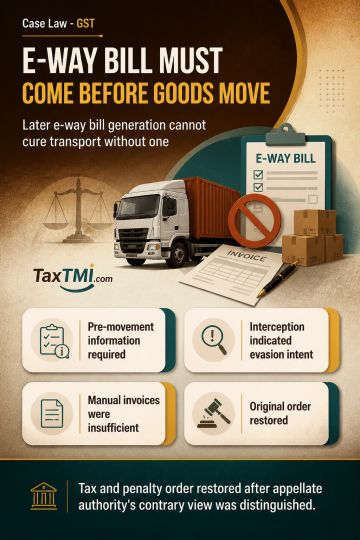
Rule 138(1) requires prescribed information to be furnished and an e-way bill generated before taxable goods begin moving. Transport without an e-way bill at interception was treated as establishing intent to evade tax, because later online generation could not cure the failure of statutory monitoring or prevent potential account manipulation. A manually issued invoice was not regarded as an equivalent safeguard. The appellate authority's contrary reliance on precedent was distinguished, and the original tax and penalty order under the detention provisions was restored.
Rule 138(1) requires prescribed information to be furnished and an e-way bill generated before taxable goods begin moving. Transport without an e-way bill at interception was treated as establishing intent to evade tax, because later online generation could not cure the failure of statutory monitoring or prevent potential account manipulation. A manually issued invoice was not regarded as an equivalent safeguard. The appellate authority's contrary reliance on precedent was distinguished, and the original tax and penalty order under the detention provisions was restored.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897