Toy balloon tariff classification: functional heading prevails over residual rubber and festive article headings, supporting penalties for deliberate ...
Customs valuation using comparable contemporaneous imports can displace declared value, while missing speaking orders require pursuit before competent...
Foreign customs declarations and importer admissions established undervaluation, supporting sequential value redetermination, differential duty, and m...
Customs seizure safeguards prevent detention-based limitation avoidance and invalidate provisional release conditions for imported vehicles under an i...
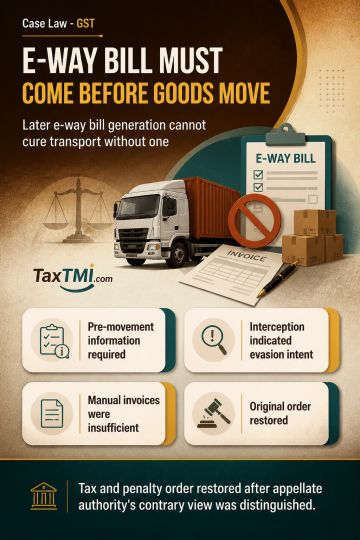
Rule 138(1) requires prescribed information to be furnished and an e-way bill generated before taxable goods begin moving. Transport without an e-way bill at interception was treated as establishing intent to evade tax, because later online generation could not cure the failure of statutory monitoring or prevent potential account manipulation. A manually issued invoice was not regarded as an equivalent safeguard. The appellate authority's contrary reliance on precedent was distinguished, and the original tax and penalty order under the detention provisions was restored.
Rule 138(1) requires prescribed information to be furnished and an e-way bill generated before taxable goods begin moving. Transport without an e-way bill at interception was treated as establishing intent to evade tax, because later online generation could not cure the failure of statutory monitoring or prevent potential account manipulation. A manually issued invoice was not regarded as an equivalent safeguard. The appellate authority's contrary reliance on precedent was distinguished, and the original tax and penalty order under the detention provisions was restored.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888