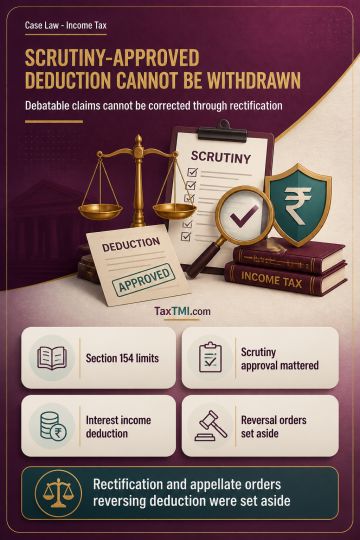
Rectification of debatable deduction claims cannot reverse scrutiny-approved co-operative society interest income deductions as apparent record errors...
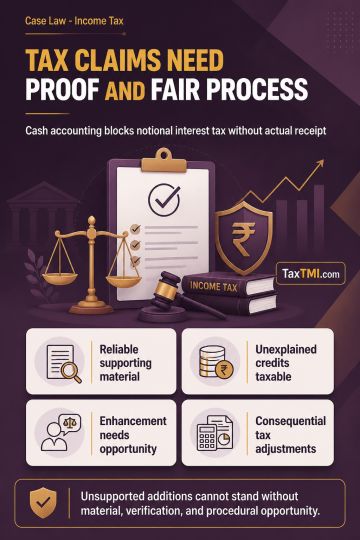
Cash-method accounting bars presumptive interest taxation, while unsupported securities and share-trading additions require reliable material and veri...
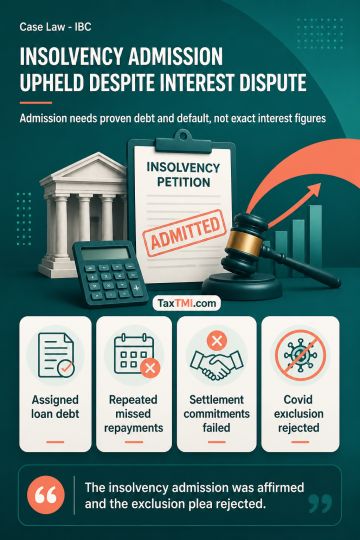
Section 7 admission requires established financial debt and default, not precise interest quantification, while post-suspension defaults remain action...
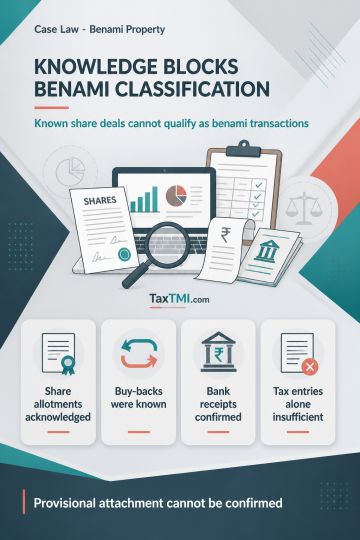
Section 2(9)(C) of the Prohibition of Benami Property Transactions Act requires the purported owner to be unaware of, or deny knowledge of, ownership. Acknowledgements by alleged benamidars during cross-examination that they knew of share allotments and buy-backs, and received the consideration in their bank accounts, prevent the transactions from meeting that requirement. Such acknowledgements prevail over conflicting statements made in income-tax proceedings. Potential tax evasion reflected in trade-payable entries does not, by itself, establish a benami transaction. Consequently, provisional attachment cannot be confirmed where the statutory knowledge requirement is not satisfied.
Section 2(9)(C) of the Prohibition of Benami Property Transactions Act requires the purported owner to be unaware of, or deny knowledge of, ownership. Acknowledgements by alleged benamidars during cross-examination that they knew of share allotments and buy-backs, and received the consideration in their bank accounts, prevent the transactions from meeting that requirement. Such acknowledgements prevail over conflicting statements made in income-tax proceedings. Potential tax evasion reflected in trade-payable entries does not, by itself, establish a benami transaction. Consequently, provisional attachment cannot be confirmed where the statutory knowledge requirement is not satisfied.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932