Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
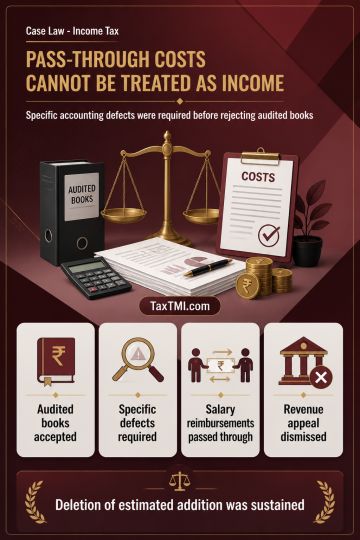
Rejection of audited books under section 145(3) requires specific defects in the accounts and cannot rest solely on non-compliance with sample third-party notices issued under section 133(6). Where the Assessing Officer verified the supplied particulars and the receipts of an HR outsourcing provider substantially comprised salary and statutory reimbursements as pass-through costs, treating total gross receipts as income and applying a fixed profit rate lacked a rational basis. The estimated addition was therefore arbitrary; deletion by the Commissioner (Appeals) was sustained and the Revenue's appeal was dismissed.
Rejection of audited books under section 145(3) requires specific defects in the accounts and cannot rest solely on non-compliance with sample third-party notices issued under section 133(6). Where the Assessing Officer verified the supplied particulars and the receipts of an HR outsourcing provider substantially comprised salary and statutory reimbursements as pass-through costs, treating total gross receipts as income and applying a fixed profit rate lacked a rational basis. The estimated addition was therefore arbitrary; deletion by the Commissioner (Appeals) was sustained and the Revenue's appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888