Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Duplicate PAN cancellation timeframe requires prior administrative representation before judicial intervention, ensuring a time-bound decision on the ...
Natural justice and pre-CIRP labour awards protect termination compensation, permitting withdrawal of court deposits despite later insolvency resoluti...
Page of 4886
Press 'Enter' after typing page number.
21 to 40 of 97705 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
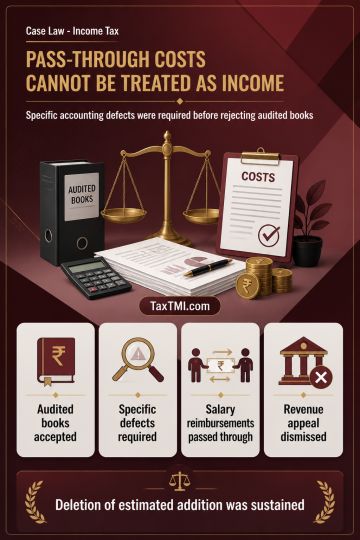
Rejection of audited books under section 145(3) requires specific defects in the accounts and cannot rest solely on non-compliance with sample third-party notices issued under section 133(6). Where the Assessing Officer verified the supplied particulars and the receipts of an HR outsourcing provider substantially comprised salary and statutory reimbursements as pass-through costs, treating total gross receipts as income and applying a fixed profit rate lacked a rational basis. The estimated addition was therefore arbitrary; deletion by the Commissioner (Appeals) was sustained and the Revenue's appeal was dismissed.
Rejection of audited books under section 145(3) requires specific defects in the accounts and cannot rest solely on non-compliance with sample third-party notices issued under section 133(6). Where the Assessing Officer verified the supplied particulars and the receipts of an HR outsourcing provider substantially comprised salary and statutory reimbursements as pass-through costs, treating total gross receipts as income and applying a fixed profit rate lacked a rational basis. The estimated addition was therefore arbitrary; deletion by the Commissioner (Appeals) was sustained and the Revenue's appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886