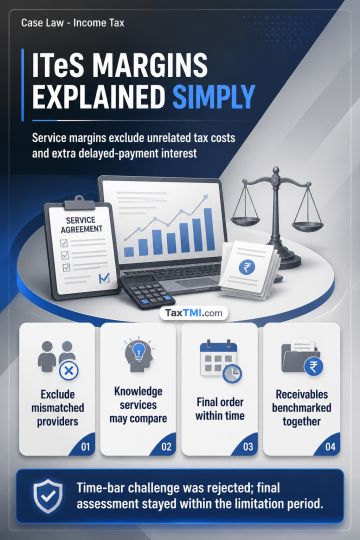
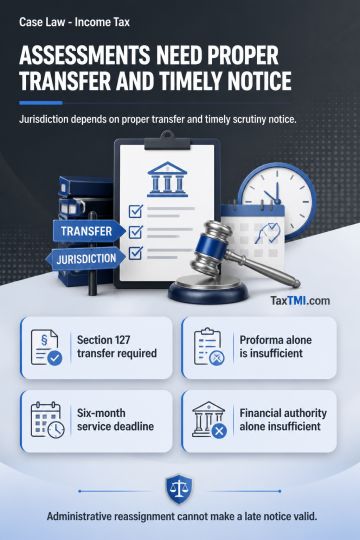
Transfer-pricing treatment of ITeS margins excludes pass-through tax recoveries and separate delayed-receivables interest after working-capital adjust...
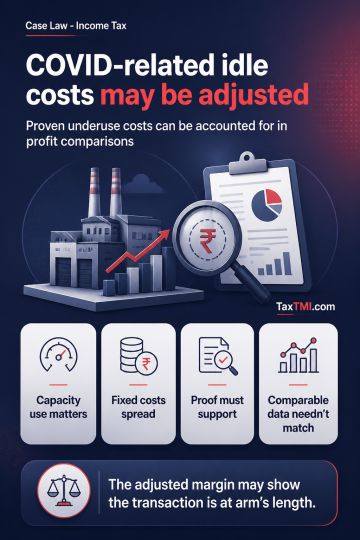
Capacity-utilisation adjustments under TNMM can neutralise substantiated COVID-related idle costs where underutilisation materially affects profitabil...
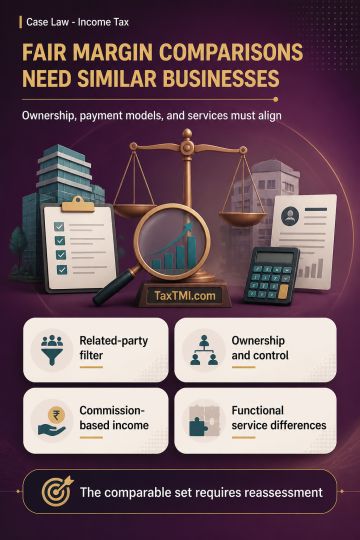
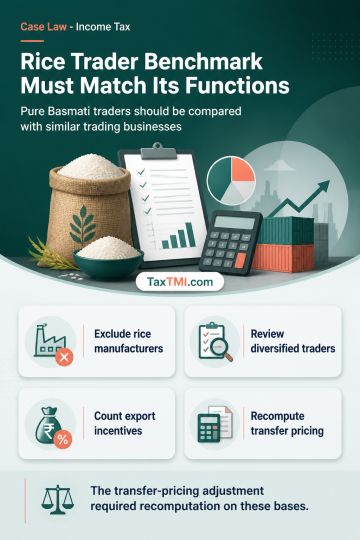
TNMM functional comparability requires excluding rice manufacturers from a pure Basmati rice trader's benchmark and recognising operating export recei...
Working-capital adjustment subsumes delayed-receivable effects in TNMM benchmarking of captive software-development services, avoiding separate notion...
Transfer-pricing comparability requires exclusion of financially illogical super-profit comparables and correction of unsupported annual-report and ma...
Charitable character assessment preserves Section 80G approval despite inclusive spiritual teachings and incidental religious expenditure within the s...
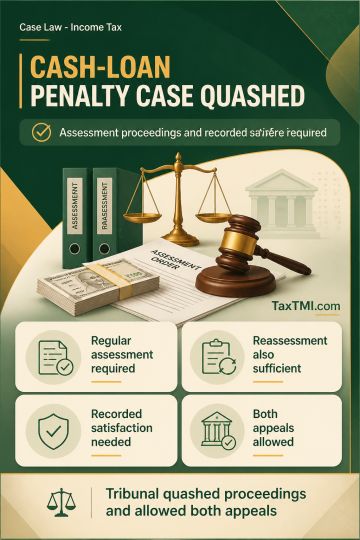
Penalty proceedings for cash-loan acceptance require assessment proceedings and recorded Assessing Officer satisfaction; absent these, the proceedings...
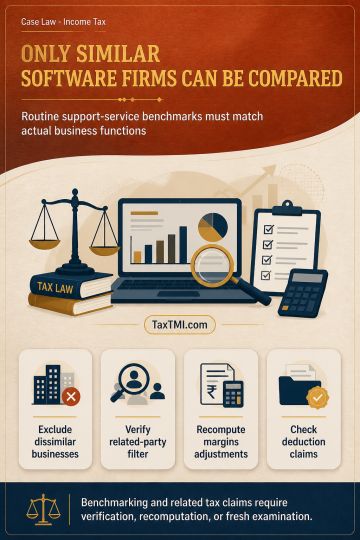
Functional comparability governs software-service benchmarking: dissimilar companies are excluded, while related-party filters, margins and working-ca...
Cheating by dishonest inducement requires a fraudulent or dishonest false representation intended to deceive, followed by the complainant acting on it through delivery of property or the requisite harm. Criminal conspiracy requires proof beyond reasonable doubt of an agreement or prior meeting of minds to commit an illegal act or a lawful act by illegal means; suspicion, association, or relationship is insufficient. Where directors are accused of corporate misconduct, cogent evidence must distinguish their individual dishonest acts, participation, or benefit from the roles of directors who were not prosecuted. Unsupported allegations of collateral security or mortgage creation do not establish dishonest inducement or conspiracy.
Cheating by dishonest inducement requires a fraudulent or dishonest false representation intended to deceive, followed by the complainant acting on it through delivery of property or the requisite harm. Criminal conspiracy requires proof beyond reasonable doubt of an agreement or prior meeting of minds to commit an illegal act or a lawful act by illegal means; suspicion, association, or relationship is insufficient. Where directors are accused of corporate misconduct, cogent evidence must distinguish their individual dishonest acts, participation, or benefit from the roles of directors who were not prosecuted. Unsupported allegations of collateral security or mortgage creation do not establish dishonest inducement or conspiracy.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4931