Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
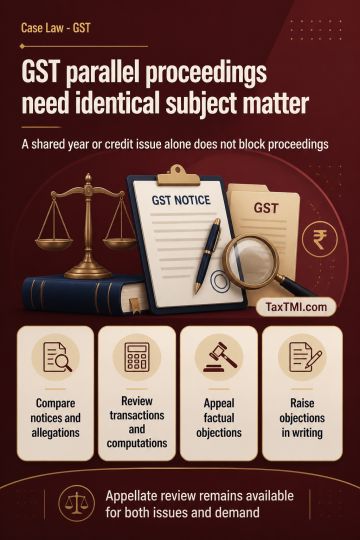
Parallel GST proceedings are barred only where Central and State proceedings concern the same subject matter. Common input tax credit issues or the same financial year alone do not establish that condition; the respective show-cause notices, allegations, transactions, computations, evidentiary material and proposed liabilities require comparison. Where an effective statutory appeal is available and the objection requires examination of the underlying record, writ jurisdiction need not be exercised. Failure to raise the objection in a written reply and participation in adjudication may be relevant to discretionary writ relief, without deciding the objection on its merits. The parallel-proceedings issue and demand challenge remain available for appellate consideration.
Parallel GST proceedings are barred only where Central and State proceedings concern the same subject matter. Common input tax credit issues or the same financial year alone do not establish that condition; the respective show-cause notices, allegations, transactions, computations, evidentiary material and proposed liabilities require comparison. Where an effective statutory appeal is available and the objection requires examination of the underlying record, writ jurisdiction need not be exercised. Failure to raise the objection in a written reply and participation in adjudication may be relevant to discretionary writ relief, without deciding the objection on its merits. The parallel-proceedings issue and demand challenge remain available for appellate consideration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI