Co-operative deduction eligibility excludes refund and commercial-bank interest, while qualifying co-operative investments require entity-wise verific...
Enhanced tax rate on surrendered unexplained income applies prospectively, while cash-deposit telescoping requires verification of available surrender...
Customs Broker licence proceedings require accurate procedural facts before delay or natural-justice findings can justify setting aside regulatory act...
Provisional assessment finalisation must precede export duty recovery, while redemption fine fails for goods already exported and unavailable for conf...
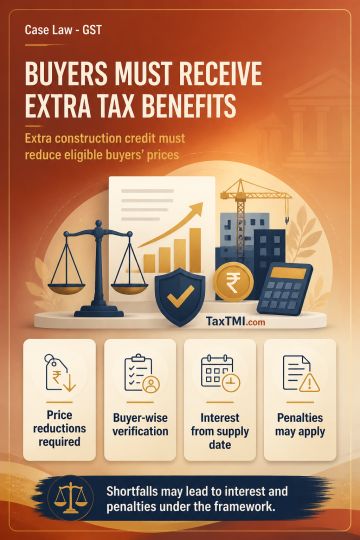
Additional input tax credit arising in a construction project must be passed to eligible buyers through commensurate price reductions under the anti-profiteering framework. Buyer-wise verification may establish that substantial credit has been passed on while identifying outstanding benefit due to remaining recipients. Unpassed benefit attracts interest from the date of supply because recipients were deprived of the monetary benefit; it cannot generally be withheld against disputed consideration where a separate consumer dispute remains pending. Continuing failure to pass on benefit after the penalty provision took effect can also attract a penalty, subject to the statutory relief available where the profiteered amount is deposited within the prescribed period.
Additional input tax credit arising in a construction project must be passed to eligible buyers through commensurate price reductions under the anti-profiteering framework. Buyer-wise verification may establish that substantial credit has been passed on while identifying outstanding benefit due to remaining recipients. Unpassed benefit attracts interest from the date of supply because recipients were deprived of the monetary benefit; it cannot generally be withheld against disputed consideration where a separate consumer dispute remains pending. Continuing failure to pass on benefit after the penalty provision took effect can also attract a penalty, subject to the statutory relief available where the profiteered amount is deposited within the prescribed period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897