Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
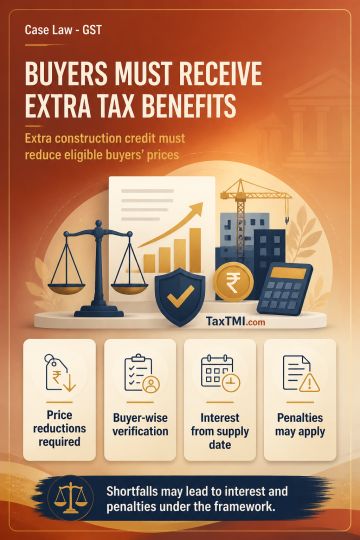
Additional input tax credit arising in a construction project must be passed to eligible buyers through commensurate price reductions under the anti-profiteering framework. Buyer-wise verification may establish that substantial credit has been passed on while identifying outstanding benefit due to remaining recipients. Unpassed benefit attracts interest from the date of supply because recipients were deprived of the monetary benefit; it cannot generally be withheld against disputed consideration where a separate consumer dispute remains pending. Continuing failure to pass on benefit after the penalty provision took effect can also attract a penalty, subject to the statutory relief available where the profiteered amount is deposited within the prescribed period.
Additional input tax credit arising in a construction project must be passed to eligible buyers through commensurate price reductions under the anti-profiteering framework. Buyer-wise verification may establish that substantial credit has been passed on while identifying outstanding benefit due to remaining recipients. Unpassed benefit attracts interest from the date of supply because recipients were deprived of the monetary benefit; it cannot generally be withheld against disputed consideration where a separate consumer dispute remains pending. Continuing failure to pass on benefit after the penalty provision took effect can also attract a penalty, subject to the statutory relief available where the profiteered amount is deposited within the prescribed period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI