Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
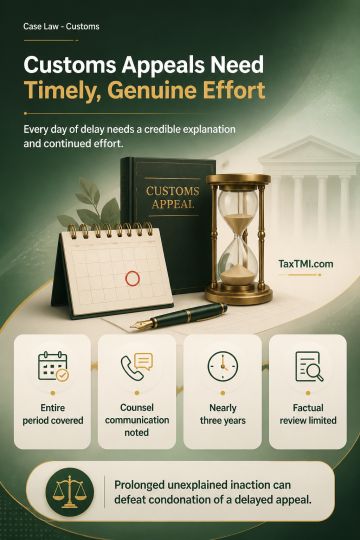
Condonation of delay in customs appeals requires a bona fide, satisfactory explanation covering the entire period of delay. Although "sufficient cause" receives a liberal, justice-oriented construction, that approach does not excuse gross negligence, lack of diligence or prolonged inaction. Participation through counsel, communication of the adjudication order to counsel, departmental efforts to serve the order, and failure to enquire about the outcome for nearly three years may support refusal of condonation; later receipt of an order copy does not explain earlier inaction. Under the Customs Act, High Court review does not permit reappreciation of such factual findings absent perversity, disregard of material evidence or legal error.
Condonation of delay in customs appeals requires a bona fide, satisfactory explanation covering the entire period of delay. Although "sufficient cause" receives a liberal, justice-oriented construction, that approach does not excuse gross negligence, lack of diligence or prolonged inaction. Participation through counsel, communication of the adjudication order to counsel, departmental efforts to serve the order, and failure to enquire about the outcome for nearly three years may support refusal of condonation; later receipt of an order copy does not explain earlier inaction. Under the Customs Act, High Court review does not permit reappreciation of such factual findings absent perversity, disregard of material evidence or legal error.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI