Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
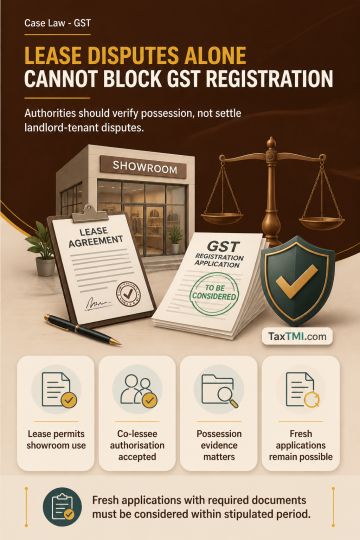
GST registration requires the registering authority to verify whether the applicant has legal possession of the business premises, without conducting a detailed adjudication of landlord-tenant disputes over the scope of lease rights. Lease documents permitting showroom operations, co-lessees' authorisation for a managing partner to form and operate a partnership firm, and landlords' own proceedings indicating the partner's possession may prima facie establish the firm's legal possession for registration purposes. Where a registration application lacks required supporting documents, a fresh application may be filed with those documents and must be considered in accordance with these principles within the stipulated period.
GST registration requires the registering authority to verify whether the applicant has legal possession of the business premises, without conducting a detailed adjudication of landlord-tenant disputes over the scope of lease rights. Lease documents permitting showroom operations, co-lessees' authorisation for a managing partner to form and operate a partnership firm, and landlords' own proceedings indicating the partner's possession may prima facie establish the firm's legal possession for registration purposes. Where a registration application lacks required supporting documents, a fresh application may be filed with those documents and must be considered in accordance with these principles within the stipulated period.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI