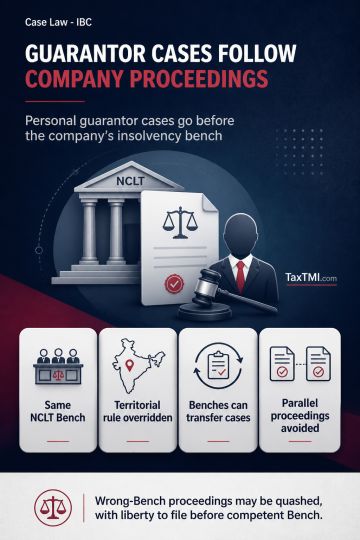
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
Special Additional Duty refund limitation under an amending customs exemption notification is addressed in relation to a claim rejected solely for filing beyond one year. The limitation was treated as requiring read-down because subordinate legislation could not impose a time bar affecting substantive refund rights without applying a statutory limitation under the parent enactment. A contrary High Court view was noted, but the refund claim was treated as covered by the decisions supporting read-down. The time-bar rejection was set aside, with consequential relief in accordance with law.
Special Additional Duty refund limitation under an amending customs exemption notification is addressed in relation to a claim rejected solely for filing beyond one year. The limitation was treated as requiring read-down because subordinate legislation could not impose a time bar affecting substantive refund rights without applying a statutory limitation under the parent enactment. A contrary High Court view was noted, but the refund claim was treated as covered by the decisions supporting read-down. The time-bar rejection was set aside, with consequential relief in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4939