Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
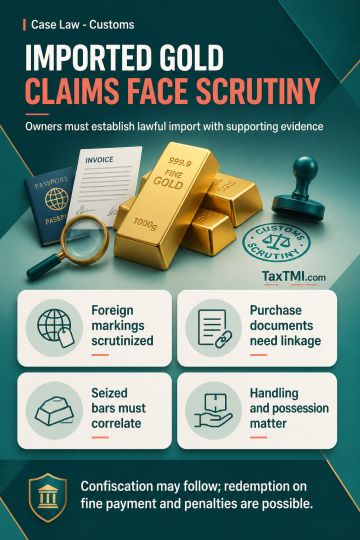
Foreign-origin gold seized under a reasonable belief of smuggling is subject to a statutory burden of proof requiring the claimant-owner to establish lawful import. Foreign markings, unsupported purchase documents and failure to correlate those documents with the seized bars may establish that this burden remains undischarged, rendering the gold liable to confiscation. Confiscation may be accompanied by redemption on payment of the adjudged fine. A person who knowingly handles, transports or possesses goods known or reasonably believed to be liable to confiscation may incur penalty. Handling and possession of gold found liable to confiscation can therefore support both confiscation-related consequences and a statutory penalty.
Foreign-origin gold seized under a reasonable belief of smuggling is subject to a statutory burden of proof requiring the claimant-owner to establish lawful import. Foreign markings, unsupported purchase documents and failure to correlate those documents with the seized bars may establish that this burden remains undischarged, rendering the gold liable to confiscation. Confiscation may be accompanied by redemption on payment of the adjudged fine. A person who knowingly handles, transports or possesses goods known or reasonably believed to be liable to confiscation may incur penalty. Handling and possession of gold found liable to confiscation can therefore support both confiscation-related consequences and a statutory penalty.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI