Charitable registration renewal cannot become an assessment of receipts, profitability or annual exemption compliance, requiring renewal and donation ...
AMP expenditure for own business is not an international transaction without an associated-enterprise arrangement, eliminating transfer pricing adjust...
Customs valuation must use comparable contemporary imports, while confiscation fines and penalties require proportionate recalculation on reassessed v...
Depositor-protection proceedings prevail over corporate insolvency, while liquidators may recover chit receivables using copies of seized company reco...
Intermediary service classification fails where overseas admission facilitation is supplied independently, preserving export treatment and small-provi...
Satellite transponder bandwidth is telecommunication, not Business Support Service; foreign non-telegraph providers triggered no service tax liability...
Page of 4897
Press 'Enter' after typing page number.
1901 to 1920 of 97923 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Corporate guarantees furnished by holding companies for...
Corporate guarantee valuation permits actual ascertainable commission while barring retroactive application and extended-period penalties for bona fide disputes.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
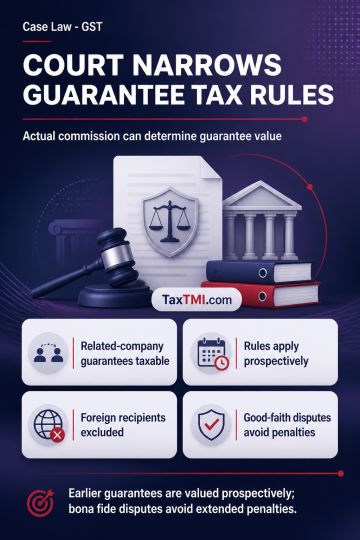
Corporate guarantees furnished by holding companies for subsidiaries constitute taxable supplies of services between related persons, including where provided without consideration. A guarantee is not an actionable claim, and a share-pledge arrangement may also amount to a guarantee where its operative terms secure the subsidiary's obligations. Gratuitous guarantees are not continuous supplies, but annual accounting disclosure may determine yearly valuation based on outstanding guaranteed debt. Rule 28(2) remains valid, but the requirement to adopt the higher of deemed value and actual consideration is read down where an actual commission is ascertainable. The valuation rule cannot apply to guarantees executed before its introduction, although continuing guarantees remain taxable prospectively; guarantees for foreign recipients fall outside the rule. Extended-period proceedings and penalties require deliberate intent to evade tax, not a bona fide interpretive dispute.
Corporate guarantees furnished by holding companies for subsidiaries constitute taxable supplies of services between related persons, including where provided without consideration. A guarantee is not an actionable claim, and a share-pledge arrangement may also amount to a guarantee where its operative terms secure the subsidiary's obligations. Gratuitous guarantees are not continuous supplies, but annual accounting disclosure may determine yearly valuation based on outstanding guaranteed debt. Rule 28(2) remains valid, but the requirement to adopt the higher of deemed value and actual consideration is read down where an actual commission is ascertainable. The valuation rule cannot apply to guarantees executed before its introduction, although continuing guarantees remain taxable prospectively; guarantees for foreign recipients fall outside the rule. Extended-period proceedings and penalties require deliberate intent to evade tax, not a bona fide interpretive dispute.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897