Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
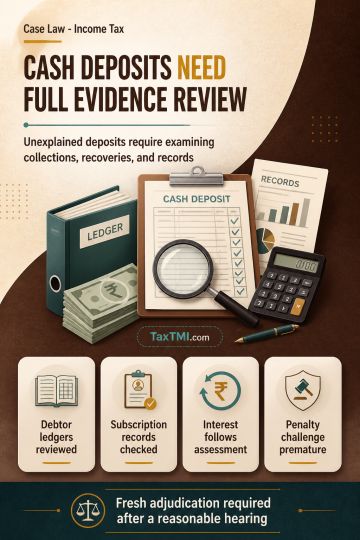
Cash-credit additions for unexplained deposits require a comprehensive examination of the taxpayer's cash-collection business model, debtor-recovery cycle, and supporting records, including debtor ledgers, subscription records, cash books and bank statements. Where such evidence has not been fully considered, the addition requires fresh adjudication after reasonable hearing, without deciding the merits or the validity of book rejection. Interest for advance-tax default is consequential to the assessment. Penalty proceedings for unexplained or under-reported income remain separate from quantum proceedings, making a challenge to their initiation premature.
Cash-credit additions for unexplained deposits require a comprehensive examination of the taxpayer's cash-collection business model, debtor-recovery cycle, and supporting records, including debtor ledgers, subscription records, cash books and bank statements. Where such evidence has not been fully considered, the addition requires fresh adjudication after reasonable hearing, without deciding the merits or the validity of book rejection. Interest for advance-tax default is consequential to the assessment. Penalty proceedings for unexplained or under-reported income remain separate from quantum proceedings, making a challenge to their initiation premature.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881