Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Page of 4897
Press 'Enter' after typing page number.
581 to 600 of 97923 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
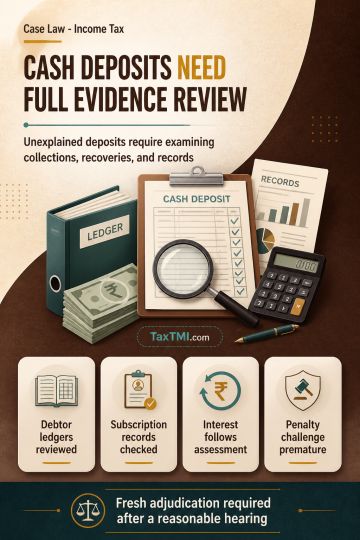
Cash-credit additions for unexplained deposits require a comprehensive examination of the taxpayer's cash-collection business model, debtor-recovery cycle, and supporting records, including debtor ledgers, subscription records, cash books and bank statements. Where such evidence has not been fully considered, the addition requires fresh adjudication after reasonable hearing, without deciding the merits or the validity of book rejection. Interest for advance-tax default is consequential to the assessment. Penalty proceedings for unexplained or under-reported income remain separate from quantum proceedings, making a challenge to their initiation premature.
Cash-credit additions for unexplained deposits require a comprehensive examination of the taxpayer's cash-collection business model, debtor-recovery cycle, and supporting records, including debtor ledgers, subscription records, cash books and bank statements. Where such evidence has not been fully considered, the addition requires fresh adjudication after reasonable hearing, without deciding the merits or the validity of book rejection. Interest for advance-tax default is consequential to the assessment. Penalty proceedings for unexplained or under-reported income remain separate from quantum proceedings, making a challenge to their initiation premature.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897