Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
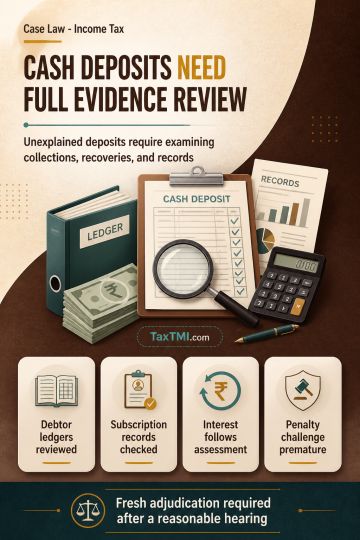
Cash-credit additions for unexplained deposits require a comprehensive examination of the taxpayer's cash-collection business model, debtor-recovery cycle, and supporting records, including debtor ledgers, subscription records, cash books and bank statements. Where such evidence has not been fully considered, the addition requires fresh adjudication after reasonable hearing, without deciding the merits or the validity of book rejection. Interest for advance-tax default is consequential to the assessment. Penalty proceedings for unexplained or under-reported income remain separate from quantum proceedings, making a challenge to their initiation premature.
Cash-credit additions for unexplained deposits require a comprehensive examination of the taxpayer's cash-collection business model, debtor-recovery cycle, and supporting records, including debtor ledgers, subscription records, cash books and bank statements. Where such evidence has not been fully considered, the addition requires fresh adjudication after reasonable hearing, without deciding the merits or the validity of book rejection. Interest for advance-tax default is consequential to the assessment. Penalty proceedings for unexplained or under-reported income remain separate from quantum proceedings, making a challenge to their initiation premature.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888