Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
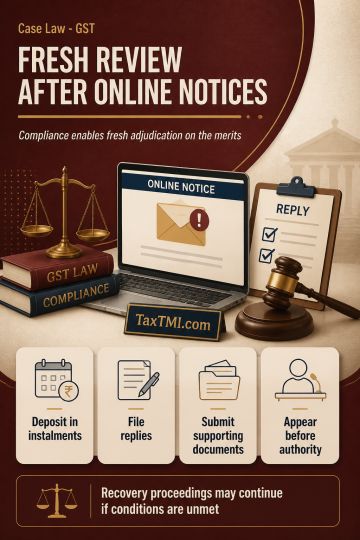
Assessment orders passed after non-response to portal-issued show-cause notices were quashed after the assessee agreed to make the stipulated deposit in instalments and appear before the assessing authority. The assessee may file replies and supporting documents, with the impugned assessment orders treated as addenda to the respective show-cause notices. Fresh adjudication on merits is conditional on compliance with the deposit and reply-filing requirements. If those conditions are not met, recovery proceedings may continue as though the writ petitions had been dismissed in limine.
Assessment orders passed after non-response to portal-issued show-cause notices were quashed after the assessee agreed to make the stipulated deposit in instalments and appear before the assessing authority. The assessee may file replies and supporting documents, with the impugned assessment orders treated as addenda to the respective show-cause notices. Fresh adjudication on merits is conditional on compliance with the deposit and reply-filing requirements. If those conditions are not met, recovery proceedings may continue as though the writ petitions had been dismissed in limine.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI