Delayed transport documents failed to validate intercepted goods, sustaining transit-state penalties where the claimed interstate destination remained...
Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Page of 4934
Press 'Enter' after typing page number.
321 to 340 of 98666 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
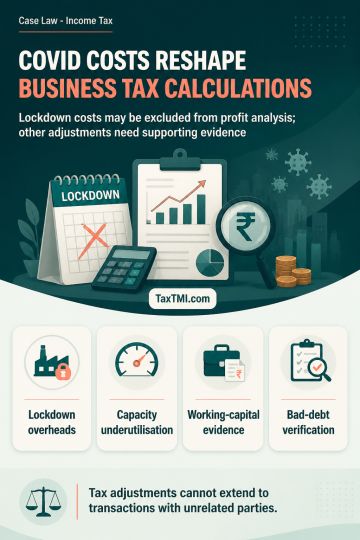
COVID-19-related fixed overheads incurred during lockdown to retain employees and maintain business continuity were treated as extraordinary, non-operating costs and excluded from the tested party's operating cost for TNMM profitability analysis. Capacity underutilisation may warrant an adjustment; where comparable companies' data is not publicly available, transfer-pricing authorities should obtain it before determining the adjustment. Transfer-pricing adjustments under Chapter X are confined to international transactions with associated enterprises and cannot extend to unrelated-party transactions. Bad-debt double-addition claims require verification where the amount was allegedly already offered to tax. Working-capital adjustments require evidence that differences materially affected price, cost or profits; absent that evidence, reconsideration depends on furnishing supporting particulars.
COVID-19-related fixed overheads incurred during lockdown to retain employees and maintain business continuity were treated as extraordinary, non-operating costs and excluded from the tested party's operating cost for TNMM profitability analysis. Capacity underutilisation may warrant an adjustment; where comparable companies' data is not publicly available, transfer-pricing authorities should obtain it before determining the adjustment. Transfer-pricing adjustments under Chapter X are confined to international transactions with associated enterprises and cannot extend to unrelated-party transactions. Bad-debt double-addition claims require verification where the amount was allegedly already offered to tax. Working-capital adjustments require evidence that differences materially affected price, cost or profits; absent that evidence, reconsideration depends on furnishing supporting particulars.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4934