Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
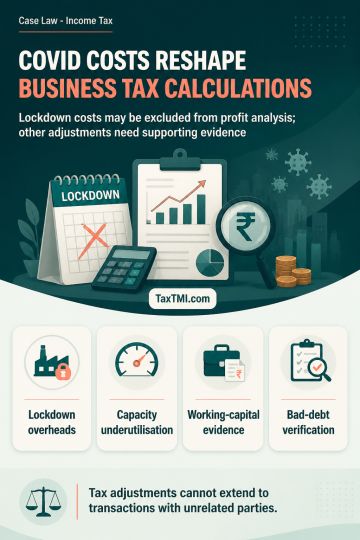
COVID-19-related fixed overheads incurred during lockdown to retain employees and maintain business continuity were treated as extraordinary, non-operating costs and excluded from the tested party's operating cost for TNMM profitability analysis. Capacity underutilisation may warrant an adjustment; where comparable companies' data is not publicly available, transfer-pricing authorities should obtain it before determining the adjustment. Transfer-pricing adjustments under Chapter X are confined to international transactions with associated enterprises and cannot extend to unrelated-party transactions. Bad-debt double-addition claims require verification where the amount was allegedly already offered to tax. Working-capital adjustments require evidence that differences materially affected price, cost or profits; absent that evidence, reconsideration depends on furnishing supporting particulars.
COVID-19-related fixed overheads incurred during lockdown to retain employees and maintain business continuity were treated as extraordinary, non-operating costs and excluded from the tested party's operating cost for TNMM profitability analysis. Capacity underutilisation may warrant an adjustment; where comparable companies' data is not publicly available, transfer-pricing authorities should obtain it before determining the adjustment. Transfer-pricing adjustments under Chapter X are confined to international transactions with associated enterprises and cannot extend to unrelated-party transactions. Bad-debt double-addition claims require verification where the amount was allegedly already offered to tax. Working-capital adjustments require evidence that differences materially affected price, cost or profits; absent that evidence, reconsideration depends on furnishing supporting particulars.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI