Government water works contract GST concession applied before its withdrawal, while contractual tax reimbursement claims lay outside advance-ruling sc...
Stamp valuation increases after registration-fee payment led to deletion of property-purchase addition within tolerance and without valuation referral...
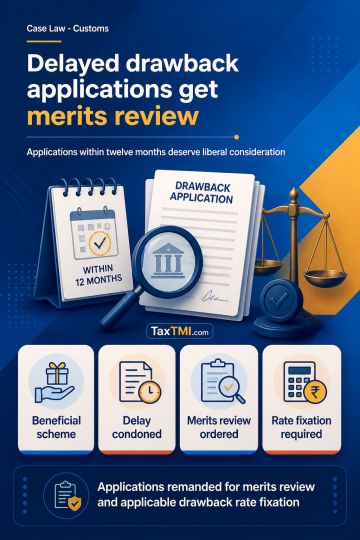
Drawback Brand Rate and Special Brand Rate applications filed after the initial period but within twelve months of the Let Export Order require liberal consideration because the drawback scheme is beneficial in nature. A narrow or technical approach to delay within the statutorily extendable period is inappropriate. Delay in the relevant applications was condoned, and the applications were remanded for consideration on merits and fixation of the applicable drawback rate in accordance with law, with consequential relief.
Drawback Brand Rate and Special Brand Rate applications filed after the initial period but within twelve months of the Let Export Order require liberal consideration because the drawback scheme is beneficial in nature. A narrow or technical approach to delay within the statutorily extendable period is inappropriate. Delay in the relevant applications was condoned, and the applications were remanded for consideration on merits and fixation of the applicable drawback rate in accordance with law, with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI