Appellate jurisdiction over baggage imports is excluded, requiring confiscation challenges involving passenger-carried gold to proceed by statutory re...
Article 227 review permits intervention in arbitration only for manifest, patent inherent jurisdictional defects, not representational authority dispu...
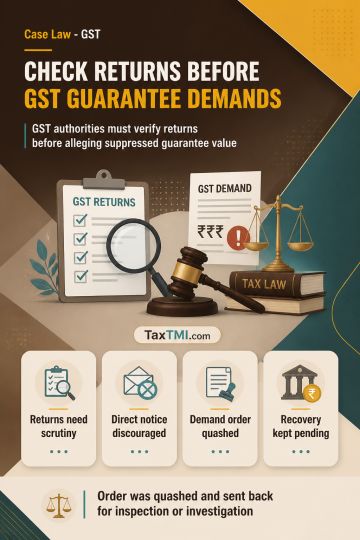
GST demand alleging suppression of taxable value in bank guarantees should follow scrutiny and verification of self-assessment returns. The GST framework permits scrutiny, audit, special audit, inspection and investigation to identify possible revenue leakage; a Form GST DRC-01 notice should not be issued directly without first undertaking the relevant exercise. The demand order discussed was quashed and remitted for inspection or investigation and, if warranted, fresh determination of revenue leakage from guarantees issued to customers. The valuation and taxability issues concerning corporate guarantees were left open. Limitation exclusion was directed for the intervening period, and recovery remained in abeyance pending the statutory exercise.
GST demand alleging suppression of taxable value in bank guarantees should follow scrutiny and verification of self-assessment returns. The GST framework permits scrutiny, audit, special audit, inspection and investigation to identify possible revenue leakage; a Form GST DRC-01 notice should not be issued directly without first undertaking the relevant exercise. The demand order discussed was quashed and remitted for inspection or investigation and, if warranted, fresh determination of revenue leakage from guarantees issued to customers. The valuation and taxability issues concerning corporate guarantees were left open. Limitation exclusion was directed for the intervening period, and recovery remained in abeyance pending the statutory exercise.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI