Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
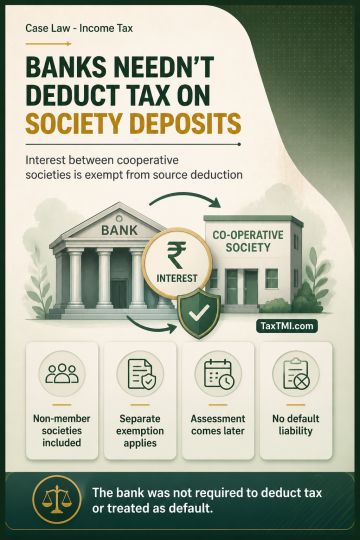
Interest paid by a co-operative bank to another co-operative society, including a non-member depositor society, falls within the inter-co-operative-society exemption from tax deduction at source. The exclusion of co-operative banks from the member-payment limb does not extend to the separate limb covering payments between co-operative societies; a co-operative bank retains its character as a co-operative society. The recipient society's eligibility for deduction of its income is determined at assessment stage and does not govern the payer's independent transactional withholding obligation. Accordingly, the co-operative bank was not required to deduct tax on such interest and could not be treated as an assessee in default.
Interest paid by a co-operative bank to another co-operative society, including a non-member depositor society, falls within the inter-co-operative-society exemption from tax deduction at source. The exclusion of co-operative banks from the member-payment limb does not extend to the separate limb covering payments between co-operative societies; a co-operative bank retains its character as a co-operative society. The recipient society's eligibility for deduction of its income is determined at assessment stage and does not govern the payer's independent transactional withholding obligation. Accordingly, the co-operative bank was not required to deduct tax on such interest and could not be treated as an assessee in default.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI