Appellate jurisdiction over baggage imports is excluded, requiring confiscation challenges involving passenger-carried gold to proceed by statutory re...
Article 227 review permits intervention in arbitration only for manifest, patent inherent jurisdictional defects, not representational authority dispu...
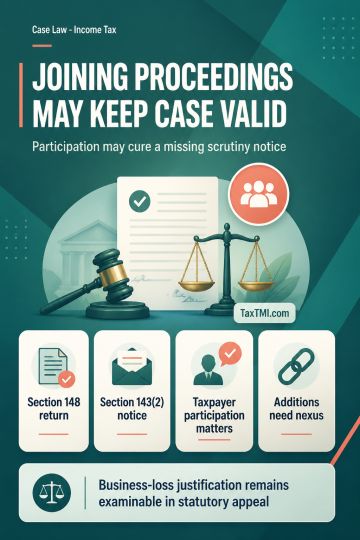
Reassessment proceedings initiated by a notice under section 148 treat the return filed in response as a return under section 139. A notice under section 143(2) is required only where the Assessing Officer considers verification necessary or expedient; its absence does not by itself invalidate reassessment, particularly where the taxpayer participated in the proceedings and section 292BB applies. Additions made during reassessment must retain a direct nexus with the recorded reasons for reopening. Where a claimed business loss is set off against unreported non-compete income forming the basis for reopening, examination of that loss is connected to the recorded reasons; the substantive justification remains examinable in statutory appeal.
Reassessment proceedings initiated by a notice under section 148 treat the return filed in response as a return under section 139. A notice under section 143(2) is required only where the Assessing Officer considers verification necessary or expedient; its absence does not by itself invalidate reassessment, particularly where the taxpayer participated in the proceedings and section 292BB applies. Additions made during reassessment must retain a direct nexus with the recorded reasons for reopening. Where a claimed business loss is set off against unreported non-compete income forming the basis for reopening, examination of that loss is connected to the recorded reasons; the substantive justification remains examinable in statutory appeal.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI