Appellate jurisdiction over baggage imports is excluded, requiring confiscation challenges involving passenger-carried gold to proceed by statutory re...
Article 227 review permits intervention in arbitration only for manifest, patent inherent jurisdictional defects, not representational authority dispu...
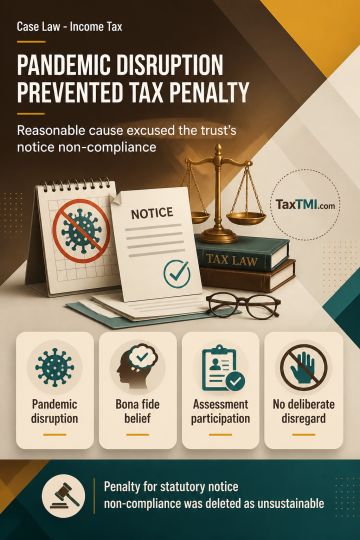
Pandemic-related disruption, a plausible bona fide belief about return-filing obligations, and subsequent participation in assessment proceedings are identified as reasonable cause for non-compliance with statutory notices by an educational trust. The note states that mere non-compliance, without independent material showing deliberate or wilful disregard, does not justify penalty. It further describes penalty provisions as quasi-criminal and inapplicable to technical or venial defaults where surrounding circumstances establish reasonable cause. On these grounds, the penalty for non-compliance with statutory notices was described as unsustainable and deleted.
Pandemic-related disruption, a plausible bona fide belief about return-filing obligations, and subsequent participation in assessment proceedings are identified as reasonable cause for non-compliance with statutory notices by an educational trust. The note states that mere non-compliance, without independent material showing deliberate or wilful disregard, does not justify penalty. It further describes penalty provisions as quasi-criminal and inapplicable to technical or venial defaults where surrounding circumstances establish reasonable cause. On these grounds, the penalty for non-compliance with statutory notices was described as unsustainable and deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI