Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
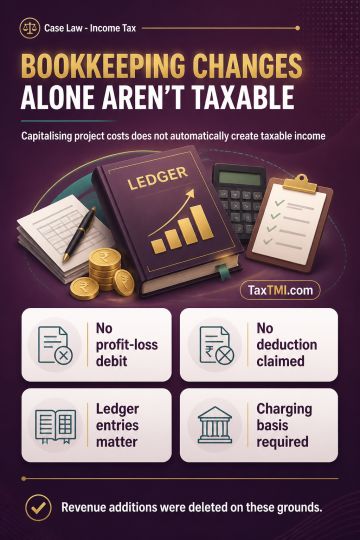
Balance-sheet reclassifications arising from capitalisation of project expenditure and reversal of duplicate entries do not, by themselves, create taxable income. Transfer of Capital Work-in-Progress or pre-operative expenditure to fixed assets is characterised as a balance-sheet movement rather than revenue expenditure where no debit is made to the Profit and Loss Account and no deduction is claimed in computing income. A reduction in an asset account cannot support an addition merely from a numerical difference; taxability requires examination of corresponding ledger entries and a demonstrated charging or deeming basis, taxable benefit, remission, or inadmissible expenditure. The notes state that the Revenue's additions were deleted on these grounds.
Balance-sheet reclassifications arising from capitalisation of project expenditure and reversal of duplicate entries do not, by themselves, create taxable income. Transfer of Capital Work-in-Progress or pre-operative expenditure to fixed assets is characterised as a balance-sheet movement rather than revenue expenditure where no debit is made to the Profit and Loss Account and no deduction is claimed in computing income. A reduction in an asset account cannot support an addition merely from a numerical difference; taxability requires examination of corresponding ledger entries and a demonstrated charging or deeming basis, taxable benefit, remission, or inadmissible expenditure. The notes state that the Revenue's additions were deleted on these grounds.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI