Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Page of 4858
Press 'Enter' after typing page number.
1 to 20 of 97155 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
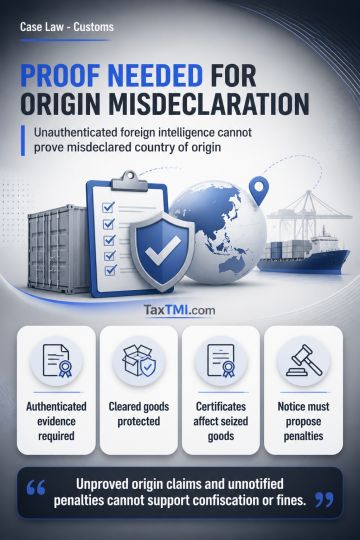
Revenue must prove country-of-origin misdeclaration through reliable, authenticated evidence; unauthenticated foreign customs intelligence and unsupported electronic material may trigger investigation but cannot conclusively establish origin. Where origin misdeclaration is not proved, confiscation and related fines or penalties founded on that allegation cannot stand. Goods already cleared for home consumption after examination cannot subsequently be confiscated for absence of phytosanitary certificates because they cease to be imported goods. Seized goods lacking the required certificate remain liable to confiscation, but may be released on redemption and production of the certificate. A penalty cannot be imposed under Section 112 unless the show cause notice proposed that penalty.
Revenue must prove country-of-origin misdeclaration through reliable, authenticated evidence; unauthenticated foreign customs intelligence and unsupported electronic material may trigger investigation but cannot conclusively establish origin. Where origin misdeclaration is not proved, confiscation and related fines or penalties founded on that allegation cannot stand. Goods already cleared for home consumption after examination cannot subsequently be confiscated for absence of phytosanitary certificates because they cease to be imported goods. Seized goods lacking the required certificate remain liable to confiscation, but may be released on redemption and production of the certificate. A penalty cannot be imposed under Section 112 unless the show cause notice proposed that penalty.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI