Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
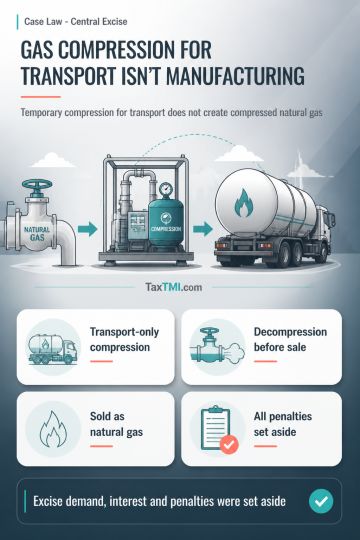
Compression of natural gas constitutes manufacture under Chapter Note 5 to Chapter 27 only where it is compressed for marketing as compressed natural gas. Compression undertaken solely to facilitate transportation, followed by decompression at customers' premises and sale as natural gas, does not amount to manufacture under section 2(f) of the Central Excise Act, 1944. On that basis, the excise duty demand, interest and penalties on the company, including the penalty imposed on its Chairman-CEO, were set aside.
Compression of natural gas constitutes manufacture under Chapter Note 5 to Chapter 27 only where it is compressed for marketing as compressed natural gas. Compression undertaken solely to facilitate transportation, followed by decompression at customers' premises and sale as natural gas, does not amount to manufacture under section 2(f) of the Central Excise Act, 1944. On that basis, the excise duty demand, interest and penalties on the company, including the penalty imposed on its Chairman-CEO, were set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI