Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
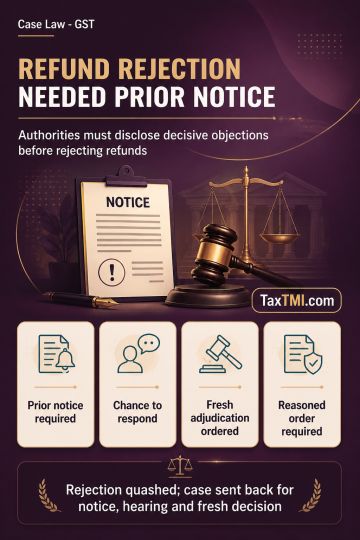
A refund claim for excess service tax cannot be rejected on an objection not disclosed to the assessee through a show cause notice. Although a Tribunal finding of refund eligibility with consequential relief does not require automatic disbursement and permits examination of legal impediments, including notification conditions and unjust enrichment, the adjudicating authority must give the assessee an opportunity to respond to any objection concerning tax paid on an abated value while CENVAT credit was availed. The High Court quashed the rejection and required fresh adjudication after notice, hearing and a reasoned order.
A refund claim for excess service tax cannot be rejected on an objection not disclosed to the assessee through a show cause notice. Although a Tribunal finding of refund eligibility with consequential relief does not require automatic disbursement and permits examination of legal impediments, including notification conditions and unjust enrichment, the adjudicating authority must give the assessee an opportunity to respond to any objection concerning tax paid on an abated value while CENVAT credit was availed. The High Court quashed the rejection and required fresh adjudication after notice, hearing and a reasoned order.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI