Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
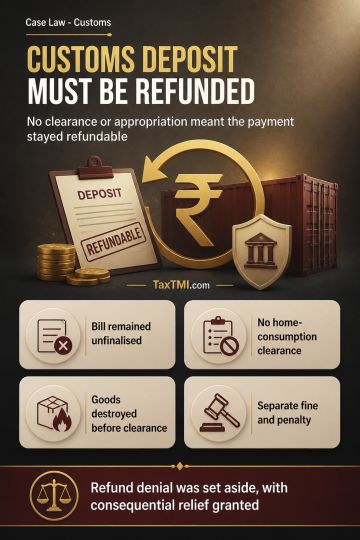
An amount paid at import remains a refundable deposit where the bill of entry is unfinalised, no out-of-charge order for home consumption is issued, and the amount is not appropriated as customs duty. The imported pillow and duvet goods failed statutory quarantine requirements and were destroyed before clearance. As redemption fine and penalty were separately imposed and paid for the goods-related illegality, the pre-clearance deposit could not be retained as duty. The refund denial was set aside, and refund was granted with consequential relief in accordance with law.
An amount paid at import remains a refundable deposit where the bill of entry is unfinalised, no out-of-charge order for home consumption is issued, and the amount is not appropriated as customs duty. The imported pillow and duvet goods failed statutory quarantine requirements and were destroyed before clearance. As redemption fine and penalty were separately imposed and paid for the goods-related illegality, the pre-clearance deposit could not be retained as duty. The refund denial was set aside, and refund was granted with consequential relief in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI