Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Page of 4858
Press 'Enter' after typing page number.
1 to 20 of 97155 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
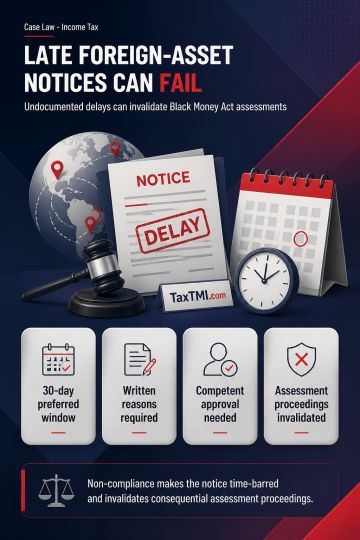
CBDT guidelines on notice timing under the Black Money Act require a notice for an alleged undisclosed foreign asset to be issued preferably within 30 days after the relevant previous year ends. Although the Act prescribes no statutory limitation period, any departure from the guideline requires recorded written reasons and approval from the competent authority. Where the tax department already possessed and acted on the relevant foreign-asset information, a later notice issued without documented reasons for delay or required approval contravenes the binding guidelines. The notes state that such non-compliance renders the notice time-barred and invalidates the consequential assessment proceedings.
CBDT guidelines on notice timing under the Black Money Act require a notice for an alleged undisclosed foreign asset to be issued preferably within 30 days after the relevant previous year ends. Although the Act prescribes no statutory limitation period, any departure from the guideline requires recorded written reasons and approval from the competent authority. Where the tax department already possessed and acted on the relevant foreign-asset information, a later notice issued without documented reasons for delay or required approval contravenes the binding guidelines. The notes state that such non-compliance renders the notice time-barred and invalidates the consequential assessment proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI