Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
A paper-form assessment order is treated as duly authenticated...
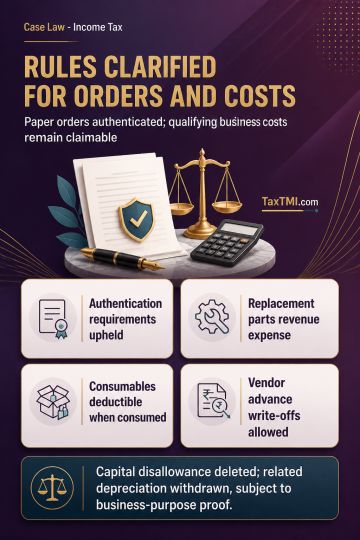
Authentication of paper assessment orders upheld, while qualifying repairs, consumables and vendor advance write-offs remain deductible business claims.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
A paper-form assessment order is treated as duly authenticated where it bears the authorised signatory's name, designation, signature, date and Document Identification Number; any procedural defect may also be protected by section 292B. Expenditure on replacement parts for existing plant and machinery is revenue expenditure where no new asset or enduring benefit is established, requiring deletion of the capital disallowance and withdrawal of related depreciation. Documented shop-floor consumables are deductible on consumption. Relief-fund contributions require proof that they were incurred wholly and exclusively for business purposes. Vendor advances for undelivered materials may be written off as business loss where their business nexus is undisputed.
A paper-form assessment order is treated as duly authenticated where it bears the authorised signatory's name, designation, signature, date and Document Identification Number; any procedural defect may also be protected by section 292B. Expenditure on replacement parts for existing plant and machinery is revenue expenditure where no new asset or enduring benefit is established, requiring deletion of the capital disallowance and withdrawal of related depreciation. Documented shop-floor consumables are deductible on consumption. Relief-fund contributions require proof that they were incurred wholly and exclusively for business purposes. Vendor advances for undelivered materials may be written off as business loss where their business nexus is undisputed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI