Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
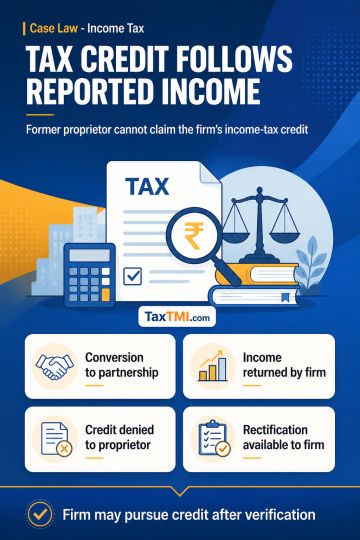
TDS credit under section 199 must follow the person who has offered the corresponding income to tax. Where a proprietorship is converted into a partnership firm but clients continue deducting tax under the former proprietor's PAN, the individual proprietor cannot claim credit if the related income was returned by the firm. The firm may seek the credit through rectification for the relevant years, subject to verification that it offered the income and that the credit is otherwise admissible. The material describes denial of credit to the individual while permitting the firm to pursue the corresponding credit.
TDS credit under section 199 must follow the person who has offered the corresponding income to tax. Where a proprietorship is converted into a partnership firm but clients continue deducting tax under the former proprietor's PAN, the individual proprietor cannot claim credit if the related income was returned by the firm. The firm may seek the credit through rectification for the relevant years, subject to verification that it offered the income and that the credit is otherwise admissible. The material describes denial of credit to the individual while permitting the firm to pursue the corresponding credit.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI