Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
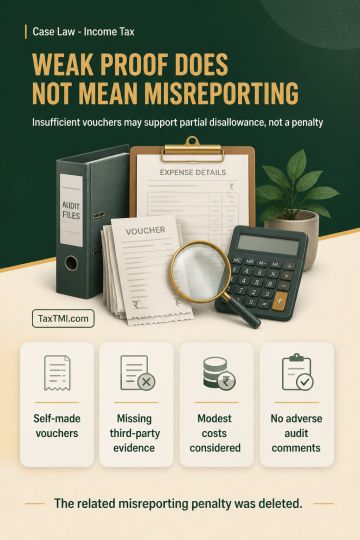
Marketing expenditure supported only by self-made vouchers may be disallowed where third-party evidence is absent, but a complete disallowance may be inappropriate when the expenditure is modest relative to turnover, relates to client visits and outstation costs, and audited books contain no adverse comments. The discussion notes that a restricted disallowance was sustained. It further explains that insufficient substantiation of an expenditure claim does not itself establish misreporting under section 270A unless a statutory category, such as misrepresentation, suppression of facts, lack of evidence, or a false book entry, is identified. The related misreporting penalty was deleted.
Marketing expenditure supported only by self-made vouchers may be disallowed where third-party evidence is absent, but a complete disallowance may be inappropriate when the expenditure is modest relative to turnover, relates to client visits and outstation costs, and audited books contain no adverse comments. The discussion notes that a restricted disallowance was sustained. It further explains that insufficient substantiation of an expenditure claim does not itself establish misreporting under section 270A unless a statutory category, such as misrepresentation, suppression of facts, lack of evidence, or a false book entry, is identified. The related misreporting penalty was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI