Loading...

Top
Help
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback

Contact Us At :

E-mail: [email protected]

Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
Add to...
You have not created any category. Kindly create one to bookmark this item!
Create New Category
Hide
Title :
Description :
❮❮ Hide
Default View
Expand ❯❯
Close ✕
🔎 Highlights - Adv. Search
TEXT SEARCH:

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In:
Main Text + AI Text
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws----
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ----
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ----
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
    Admitted cheque signature in dishonour prosecutions activates presumptions of consideration and debt, requiring an evidence-based probable defence.
    Regular bail after charge-sheet filing granted where custody was no longer required in alleged GST input-tax-credit fraud.
    Duty-free shop sales remain subject to domestic regulatory laws, while nicotine pouch licensing requires product-specific classification assessment.
    Prospective GST liability limits tax on taxi-stand land rentals, while allotment claims require a reasoned determination.
    E-way bill delivery-address compliance supports Section 129 penalties even where tax is paid and the address is later registered.
    Contractual GST allocation: Writ remedy upheld where acceptance terms required GST payment beyond quoted rates.
    Kerala Flood Cess refund limitation runs from correct remittance, treating claims filed within the statutory period as timely.
    Printing on customer-owned inputs qualifies under Heading 9988, while printer-supplied religious book printing attracts residual-rate GST.
    Project management services for government infrastructure remain taxable, and invoices must identify the administrative department as recipient.
    NSQF-aligned vocational training qualifies for GST exemption when supplied by appropriately accredited bodies under approved qualification packages.
    Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
    Genuine hardship permits condonation of delayed Form 10B where bona fide compliance misunderstanding would otherwise defeat charitable exemption.
    Natural justice breaches in import-data additions justified staying recovery while appeal remained pending despite deposit guidance.
    Settlement application eligibility requires a pending assessment when filed, preventing an extra prior-eligibility condition from blocking considerati...
    Adequate Hearing in Faceless Assessments Requires the prescribed response period and meaningful personal-hearing opportunity before assessment.
    Substantial questions of law do not arise where income-tax appeals merely seek reassessment of concurrent factual findings.
    Limitation for reassessments runs from the rectification order when it directs de novo assessment, preserving timely reassessment proceedings.
    Timely return requirement for co-operative deduction supports revision where reassessment ignored eligibility linked to cash-deposit income.
    Cloud software subscription access is not royalty where no copyright or process rights transfer to subscribers.
    Bona fide disclosure and reasonable cause can prevent penalties for under-reported income and delayed tax-audit reporting.
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Deduction under section 54F is described as available where an...

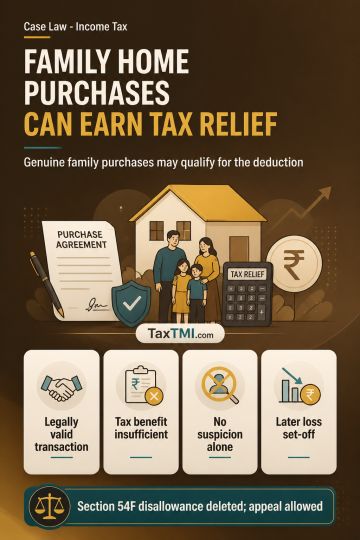
Genuine intra-family residential property purchases can qualify for section 54F deduction despite resulting tax benefits or later loss set-offs.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax July 27, 2026 Case Laws AT
Deduction under section 54F is described as available where an assessee purchases a qualifying residential property from a spouse or other relative, provided the transaction is legally valid and genuine. The notes state that tax benefit alone does not make an intra-family transaction a colourable device, and deduction cannot be denied on suspicion without material establishing a legal flaw. They further state that a spouse's later set-off of capital gains against business losses could not have been anticipated when the property transaction occurred and therefore did not justify denial. On this reasoning, the stated conclusion is that the section 54F disallowance was deleted and the appeal allowed.

Topics

Acts Income Tax