Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Revisional jurisdiction over export quota premium deductions requires both error and Revenue prejudice; a permissible assessment view cannot be displa...
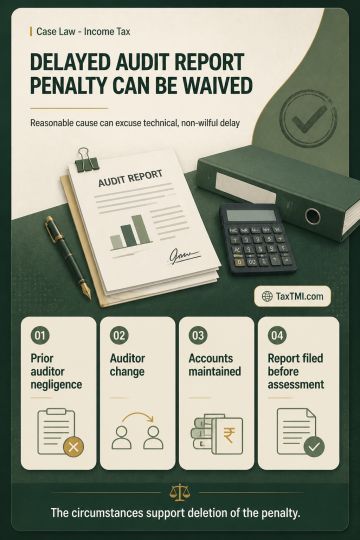
Section 273B provides that penalty for belated furnishing of a tax audit report under section 271B is not automatic where the taxpayer establishes reasonable cause. The explanation must be considered judicially to determine whether the default occurred without reasonable cause. The notes identify prior auditor negligence and a consequent change of auditor as reasonable cause where accounts were maintained, the audit was obtained, and the report was furnished before assessment concluded. A technical and venial lapse, without deliberate or wilful default or revenue loss, supports deletion of the penalty.
Section 273B provides that penalty for belated furnishing of a tax audit report under section 271B is not automatic where the taxpayer establishes reasonable cause. The explanation must be considered judicially to determine whether the default occurred without reasonable cause. The notes identify prior auditor negligence and a consequent change of auditor as reasonable cause where accounts were maintained, the audit was obtained, and the report was furnished before assessment concluded. A technical and venial lapse, without deliberate or wilful default or revenue loss, supports deletion of the penalty.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI