Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Revisional jurisdiction over export quota premium deductions requires both error and Revenue prejudice; a permissible assessment view cannot be displa...
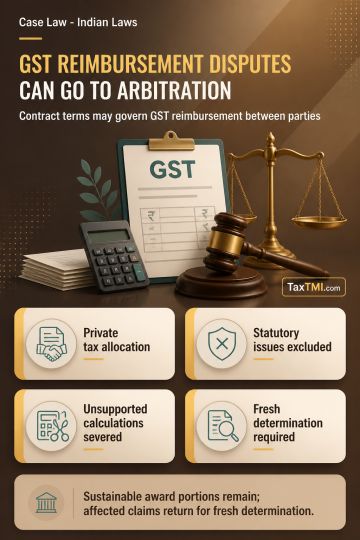
Contractual GST reimbursement disputes may be arbitrated where they concern inter se obligations such as reimbursement, tax sharing or indemnity, but not statutory tax characterisation, rates, exemptions or disputes with tax authorities. The discussion distinguishes private contractual GST allocation from matters reserved for tax administration. It further states that a tax-related SOP for EPC contracts is not incorporated merely by adopting technical specifications in an item-rate contract, particularly where binding State Government directions govern reimbursement. An award based on conjecture, incomplete findings on tax payment and loss, or disregard of transitional GST provisions may amount to patent illegality. Severable, independently sustainable portions of an award may be retained while invalid GST-related claims are remitted.
Contractual GST reimbursement disputes may be arbitrated where they concern inter se obligations such as reimbursement, tax sharing or indemnity, but not statutory tax characterisation, rates, exemptions or disputes with tax authorities. The discussion distinguishes private contractual GST allocation from matters reserved for tax administration. It further states that a tax-related SOP for EPC contracts is not incorporated merely by adopting technical specifications in an item-rate contract, particularly where binding State Government directions govern reimbursement. An award based on conjecture, incomplete findings on tax payment and loss, or disregard of transitional GST provisions may amount to patent illegality. Severable, independently sustainable portions of an award may be retained while invalid GST-related claims are remitted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI