Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
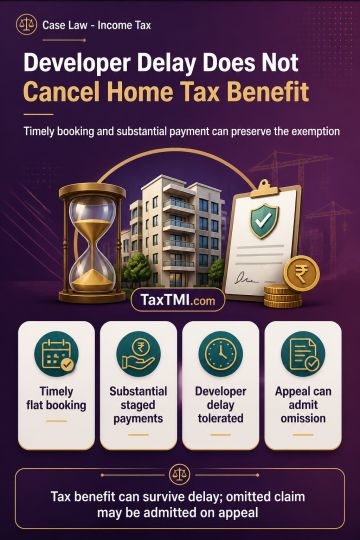
Capital-gains exemption for investment in an under-construction residential flat is discussed as available where the taxpayer books the flat promptly, substantially invests the consideration within the statutory period, and the developer's later delay causes delayed completion or registration. Allotment and staged payments are treated as construction through the developer, and a beneficial exemption is described as requiring liberal interpretation where the taxpayer has met obligations. The note also explains that an exemption claim omitted from the return may be admitted on appeal when supporting computation, booking and payment records are already on record; the restriction on fresh claims applies to the Assessing Officer, not appellate authorities.
Capital-gains exemption for investment in an under-construction residential flat is discussed as available where the taxpayer books the flat promptly, substantially invests the consideration within the statutory period, and the developer's later delay causes delayed completion or registration. Allotment and staged payments are treated as construction through the developer, and a beneficial exemption is described as requiring liberal interpretation where the taxpayer has met obligations. The note also explains that an exemption claim omitted from the return may be admitted on appeal when supporting computation, booking and payment records are already on record; the restriction on fresh claims applies to the Assessing Officer, not appellate authorities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI