Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Revisional jurisdiction over export quota premium deductions requires both error and Revenue prejudice; a permissible assessment view cannot be displa...
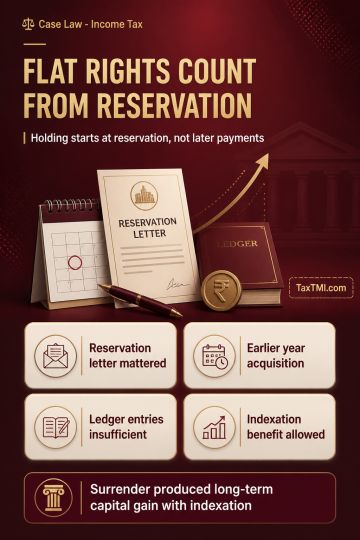
Allotment or reservation rights in a flat are treated as valuable capital assets, and their holding period is determined from the date of allotment or reservation rather than subsequent payment entries. The notes state that a reservation letter and the developer's confirmation supported acquisition of the rights in the earlier financial year, while later ledger adjustments did not displace that contemporaneous evidence. On that basis, surrender of the flat rights was characterised as giving rise to long-term capital gain, with indexation benefit, rather than short-term capital gain.
Allotment or reservation rights in a flat are treated as valuable capital assets, and their holding period is determined from the date of allotment or reservation rather than subsequent payment entries. The notes state that a reservation letter and the developer's confirmation supported acquisition of the rights in the earlier financial year, while later ledger adjustments did not displace that contemporaneous evidence. On that basis, surrender of the flat rights was characterised as giving rise to long-term capital gain, with indexation benefit, rather than short-term capital gain.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI