Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
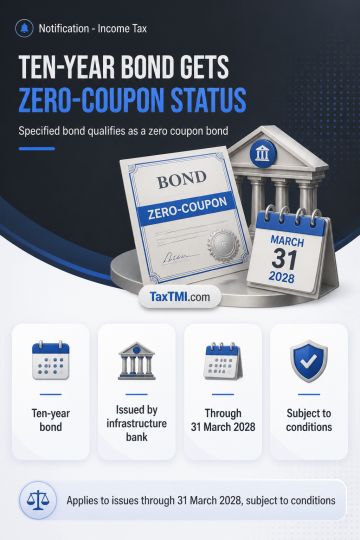
The Ten Year Zero Coupon Bond of the National Bank for Financing Infrastructure and Development is specified as a zero coupon bond for Income-tax Act purposes. The specification applies to bonds issued on or before 31 March 2028, with a ten-year life, subject to the bank satisfying the applicable conditions under the Income-tax Act, 2025 and Income-tax Rules, 2026. This gives the identified bond zero coupon bond status within the prescribed statutory and regulatory framework.
The Ten Year Zero Coupon Bond of the National Bank for Financing Infrastructure and Development is specified as a zero coupon bond for Income-tax Act purposes. The specification applies to bonds issued on or before 31 March 2028, with a ten-year life, subject to the bank satisfying the applicable conditions under the Income-tax Act, 2025 and Income-tax Rules, 2026. This gives the identified bond zero coupon bond status within the prescribed statutory and regulatory framework.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI