Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
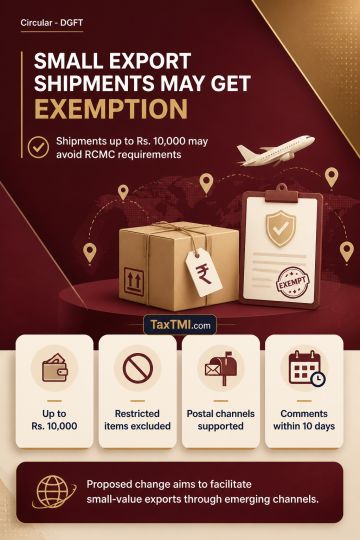
The proposed insertion of paragraph 2.57(c) of FTP 2023 would exempt export consignments with FOB value up to Rs. 10,000 from the requirement to hold a Registration-cum-Membership Certificate or Certificate of Registration when applying for FTP import/export authorisations, benefits or concessions. The exemption would not apply to items classified as restricted under ITC (HS). The proposal is intended to facilitate small-value exports, particularly through postal, courier and emerging channels, and stakeholders are invited to submit comments within 10 days of the Trade Notice.
The proposed insertion of paragraph 2.57(c) of FTP 2023 would exempt export consignments with FOB value up to Rs. 10,000 from the requirement to hold a Registration-cum-Membership Certificate or Certificate of Registration when applying for FTP import/export authorisations, benefits or concessions. The exemption would not apply to items classified as restricted under ITC (HS). The proposal is intended to facilitate small-value exports, particularly through postal, courier and emerging channels, and stakeholders are invited to submit comments within 10 days of the Trade Notice.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI