Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
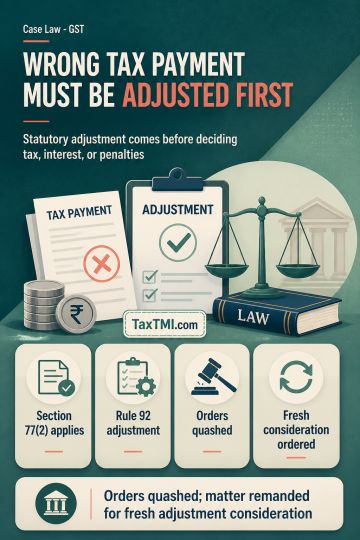
Adjustment of integrated tax paid under the wrong head against intra-State tax liability requires Section 77(2) to be read with Rule 92. Rule 92 contemplates setting off a refund entitlement against an outstanding demand through the prescribed adjustment order. The text states that an undisputed erroneous IGST payment for an intra-State supply should not create tax, interest or penalty liability without considering this adjustment mechanism. It describes the quashing of the adjudication, appellate and demand orders and remand for fresh consideration of adjustment under Section 77(2) and Rule 92.
Adjustment of integrated tax paid under the wrong head against intra-State tax liability requires Section 77(2) to be read with Rule 92. Rule 92 contemplates setting off a refund entitlement against an outstanding demand through the prescribed adjustment order. The text states that an undisputed erroneous IGST payment for an intra-State supply should not create tax, interest or penalty liability without considering this adjustment mechanism. It describes the quashing of the adjudication, appellate and demand orders and remand for fresh consideration of adjustment under Section 77(2) and Rule 92.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI