Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Revisional jurisdiction over export quota premium deductions requires both error and Revenue prejudice; a permissible assessment view cannot be displa...
Transfer-pricing analysis for software development and...
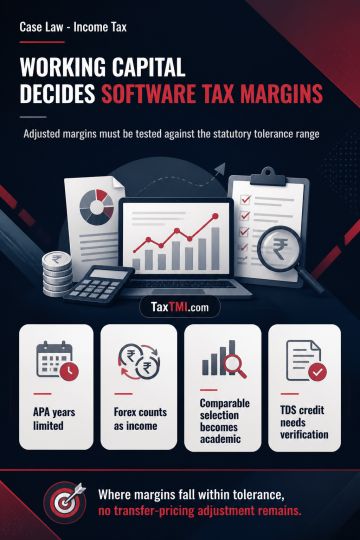
Working-capital adjustment determines whether software-services transfer-pricing margins fall within the statutory tolerance range, eliminating any adjustment.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Transfer-pricing analysis for software development and maintenance support services addresses the limits of applying an APA margin outside its covered assessment years. Foreign exchange fluctuation directly linked to those services is treated as operating income. A working-capital adjustment must be considered where supporting workings are furnished, subject to verification, and the resulting comparable margin must be tested against the statutory tolerance range; no adjustment remains if it falls within that range. Comparable-selection issues become academic on that basis. The note also addresses short credit for tax deducted at source, requiring factual verification and fresh adjudication.
Transfer-pricing analysis for software development and maintenance support services addresses the limits of applying an APA margin outside its covered assessment years. Foreign exchange fluctuation directly linked to those services is treated as operating income. A working-capital adjustment must be considered where supporting workings are furnished, subject to verification, and the resulting comparable margin must be tested against the statutory tolerance range; no adjustment remains if it falls within that range. Comparable-selection issues become academic on that basis. The note also addresses short credit for tax deducted at source, requiring factual verification and fresh adjudication.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI