Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Revisional jurisdiction over export quota premium deductions requires both error and Revenue prejudice; a permissible assessment view cannot be displa...
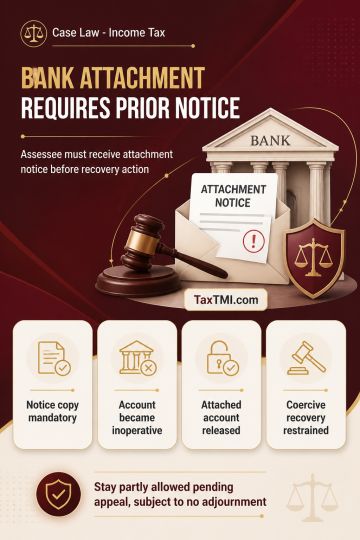
Section 226(3)(iii) requires a copy of a bank-account attachment notice to be forwarded to the assessee, with the word "shall" treated as mandatory. The notes describe an ITAT proceeding in which the assessee was not informed of the attachment before the bank account became inoperative. Applying earlier Tribunal and High Court authority, the Tribunal directed release of the attached account and restrained coercive recovery until the scheduled appeal hearing, subject to the appeal being argued without adjournment. The stay application was partly allowed.
Section 226(3)(iii) requires a copy of a bank-account attachment notice to be forwarded to the assessee, with the word "shall" treated as mandatory. The notes describe an ITAT proceeding in which the assessee was not informed of the attachment before the bank account became inoperative. Applying earlier Tribunal and High Court authority, the Tribunal directed release of the attached account and restrained coercive recovery until the scheduled appeal hearing, subject to the appeal being argued without adjournment. The stay application was partly allowed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI