Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
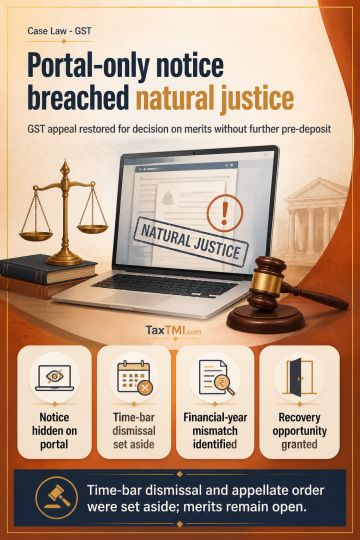
Uploading the show-cause notice only under the GST portal's 'Additional notice and orders' tab prevented a reply and violated natural justice. The HC also identified a material mismatch between the financial year covered by the appellate order and those in recovery and garnishee proceedings. It set aside the time-bar dismissal, quashed the appellate order, and required the GST appeal to be entertained and decided on merits, with all merits left open. The delay explanation was to be considered sufficient by the appellate authority, and no further pre-deposit was required. The recovery-related discrepancy warranted a further opportunity to the taxpayer.
Uploading the show-cause notice only under the GST portal's 'Additional notice and orders' tab prevented a reply and violated natural justice. The HC also identified a material mismatch between the financial year covered by the appellate order and those in recovery and garnishee proceedings. It set aside the time-bar dismissal, quashed the appellate order, and required the GST appeal to be entertained and decided on merits, with all merits left open. The delay explanation was to be considered sufficient by the appellate authority, and no further pre-deposit was required. The recovery-related discrepancy warranted a further opportunity to the taxpayer.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI