Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
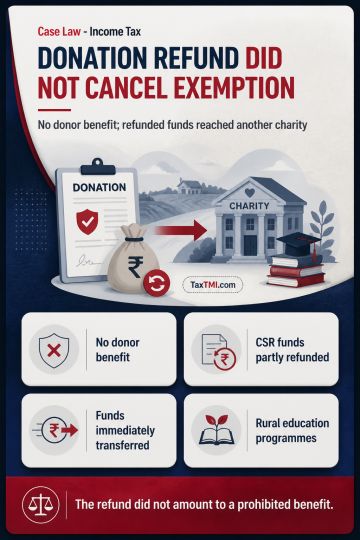
Refund of part of CSR funds by a charitable trust to its donor is examined under the prohibition on applying income or property for the benefit of specified persons. The material states that charitable exemption was not denied because there was no evidence that the donor obtained a benefit from the refund, and the amount was immediately passed to another charitable organisation conducting rural education programmes. It presents the principle that a refund, without donor benefit and followed by charitable application through another organisation, need not constitute prohibited benefit to a specified person.
Refund of part of CSR funds by a charitable trust to its donor is examined under the prohibition on applying income or property for the benefit of specified persons. The material states that charitable exemption was not denied because there was no evidence that the donor obtained a benefit from the refund, and the amount was immediately passed to another charitable organisation conducting rural education programmes. It presents the principle that a refund, without donor benefit and followed by charitable application through another organisation, need not constitute prohibited benefit to a specified person.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI